
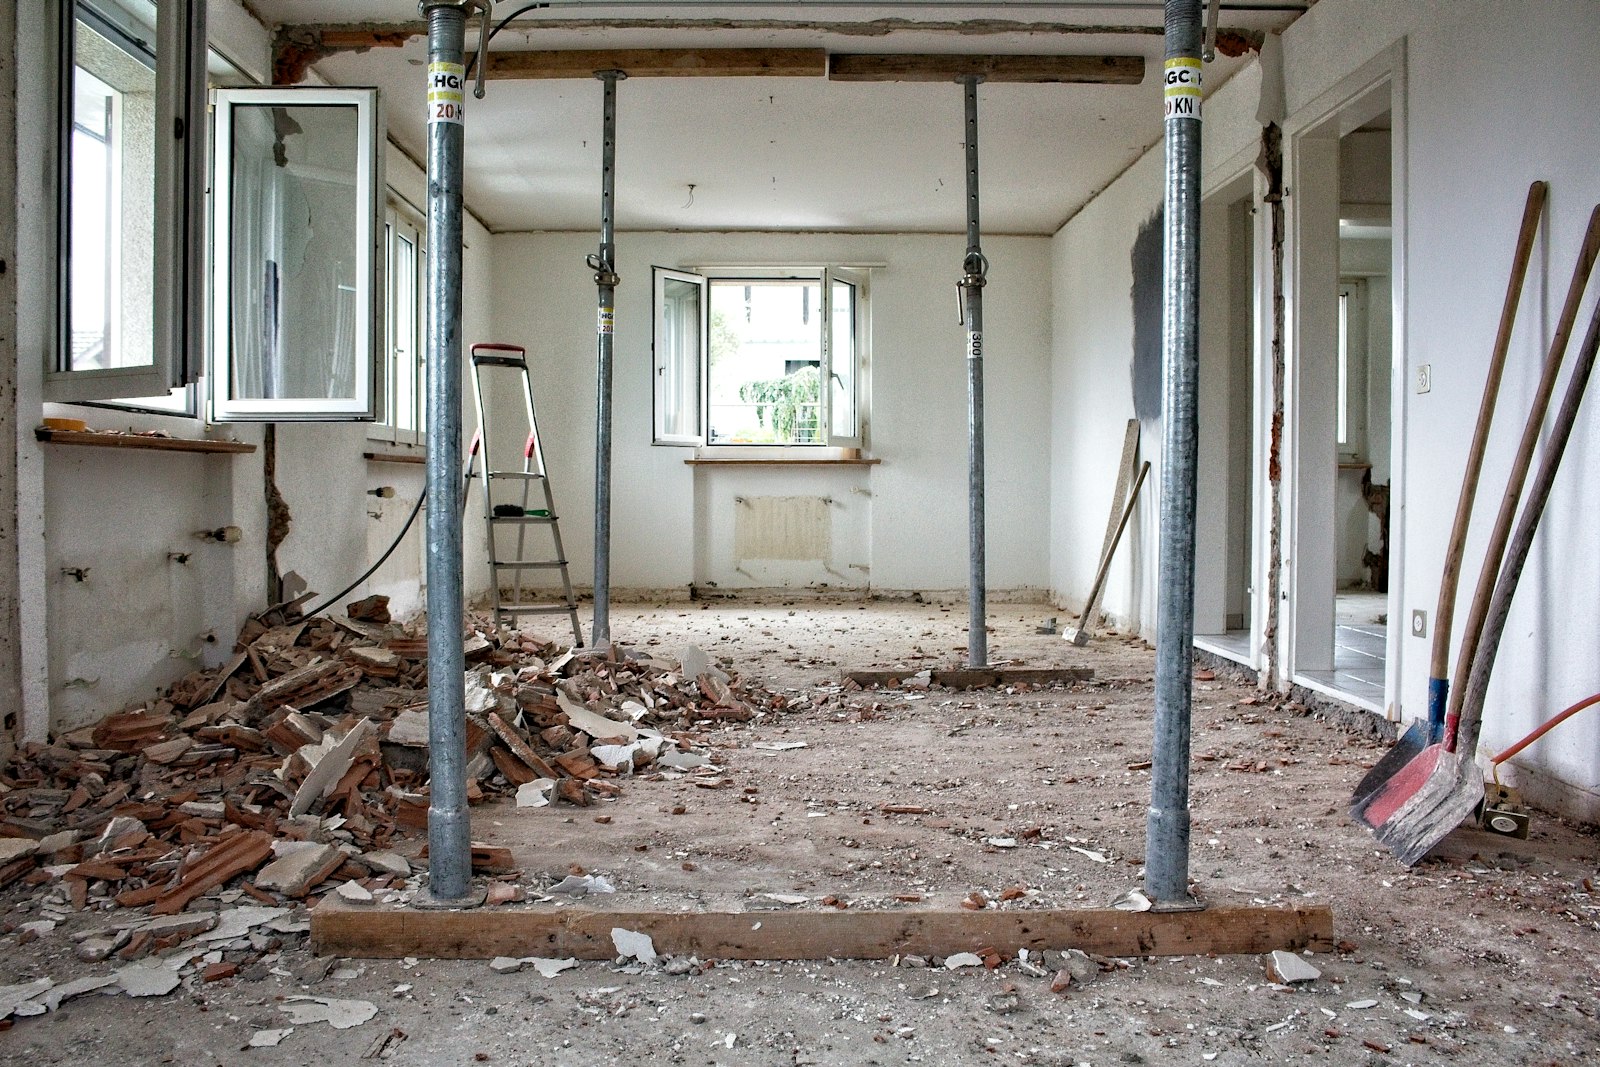
You do not need to be a contractor to learn how to estimate repair costs on a wholesale deal. You need a consistent method, a per-square-foot baseline, and the discipline to add a contingency. Your buyer will do their own estimate; yours just has to be close enough that they trust your deal sheet. Here is how to estimate repair costs in five steps, with a worked example and the mistakes that trip up most beginners.
Why your repair number matters so much
Repairs are the second number in the offer formula, right after after-repair value. Every dollar you underestimate comes straight out of your buyer’s profit, and buyers know it. If your estimate is far below theirs, they will either pass or ask for a lower price, and a lower price may be one your seller cannot accept. A repair number that is realistic, itemized, and slightly conservative is what lets a deal assign without renegotiation.
Step 1: Classify the rehab level
Walk the property (or study the photos) and put it in one of three buckets. Per-square-foot numbers below are typical ranges for a working-class single-family house in most U.S. markets; adjust for your area’s labor costs. Fire jobs break most of these rules of thumb because smoke and water damage hide behind walls, so read our guide to the fire damaged house before pricing one.
- Cosmetic ($15–$25/sq ft): paint, flooring, fixtures, landscaping, minor drywall, appliances. The house is structurally fine and the kitchen and baths are dated but functional.
- Moderate ($35–$55/sq ft): everything cosmetic plus a new kitchen, new bathrooms, and one or two major systems (roof, HVAC, water heater, electrical panel).
- Full gut ($70+/sq ft): down to the studs, all systems, layout changes, possibly foundation or structural work.
A 1,500 sq ft cosmetic rehab runs about $22,000–$37,000. The same house as a moderate rehab is $52,000–$82,000. Start there, then refine.
Treat these ranges as a starting framework, not a price list. Labor and material costs differ a lot between regions and even between neighborhoods, and they change over time. The goal of this step is only to put the house in the right bucket so your first number is in the right neighborhood before you start itemizing.
Step 2: Price the big-ticket items separately
Per-square-foot covers the interior. Five items can blow up any estimate and should be priced on their own:
- Roof: $8,000–$20,000 depending on size and material
- HVAC: $6,000–$12,000 for a full system
- Foundation: $5,000 for minor piers to $40,000+ for serious movement; get a pro opinion
- Sewer line: $4,000–$15,000; older houses with big trees are suspects
- Electrical panel and plumbing repipe: $2,500–$5,000 and $6,000–$15,000 respectively
How to spot the big items on a walkthrough
- Roof: curling or missing shingles, visible sagging, water stains on ceilings, and daylight in the attic. Ask the seller how old it is.
- HVAC: look for the data plate on the outdoor unit and furnace; the manufacture date is often printed there. Units near the end of their service life should be budgeted for replacement.
- Foundation: diagonal cracks above doors and windows, doors that stick or will not latch, sloping floors, and stair-step cracks in exterior brick.
- Sewer: slow drains throughout the house, a history of backups, and large trees near the line. A camera inspection settles it.
- Electrical and plumbing: an old fuse box or a panel brand buyers avoid, ungrounded outlets, and galvanized or mixed supply pipes.
Step 3: Add a contingency
Add 10% to everything on a house you walked and 15–20% on one you only saw in photos. Every experienced buyer does this, and a deal sheet without it tells them you are new.
Contingency is not padding for its own sake. Older houses hide problems behind walls and under floors (homes built before 1978 can also bring the EPA’s lead-safe renovation rules into play), and permits, dumpsters, and price changes on materials add up. Showing the contingency as its own line, rather than burying it in each item, makes your estimate easier to read and easier for a buyer to adjust. If the house had work done in the last few months, also check for a mechanics lien from an unpaid contractor, because that bill can follow the property to the next owner.
Step 4: Sanity-check with a buyer
Send your line-item estimate to one flipper on your A-list and ask if it is in range. They will tell you in thirty seconds, and the correction is worth more than any spreadsheet. Over time, their numbers become your numbers.
If you do not have that relationship yet, start building it now. Our guide on finding cash buyers before your first deal shows how to get those contacts in place, so you have someone to check your numbers before you put a house under contract.
Step 5: How to estimate repair costs line by line
Once you have the bucket and the big items, build a simple line-item sheet room by room. It does not need to be precise to the dollar; it needs to be complete so nothing is missed. A basic structure:
- Exterior: roof, gutters, siding or paint, windows, doors, landscaping, driveway, fencing.
- Systems: HVAC, water heater, electrical panel and wiring, plumbing supply and drain lines, sewer.
- Kitchen: cabinets, counters, appliances, sink and fixtures, backsplash, lighting.
- Bathrooms: vanity, toilet, tub or shower surround, tile, fixtures, ventilation, per bathroom.
- Interior finishes: flooring, paint, drywall repair, trim, interior doors, light fixtures.
- Other: permits, debris removal, cleaning, and anything unusual you saw.
A worked example
These are example numbers to show the method. Your market’s costs will differ.
- Subject: 1,400 sq ft, three bed, one and a half bath. Dated kitchen and baths, worn carpet, structurally sound. Bucket: cosmetic, using $20/sq ft = $28,000.
- Big items: the roof shows wear and the seller says it is original, so add $12,000. The furnace is old but running; add $7,000 to replace it because a buyer will.
- Subtotal: $28,000 + $12,000 + $7,000 = $47,000.
- Contingency: you walked the house, so add 10% = $4,700.
- Repair estimate on the deal sheet: about $52,000.
That repair figure then goes into your offer math. Our guide to writing a wholesale offer shows how ARV, repairs, and your fee combine into a maximum allowable offer.
Common repair-estimate mistakes
- Pricing it like a homeowner would. Your buyer is pricing a full resale-ready renovation, not a patch job. Estimate for the finish level that comps in the area show.
- Skipping the systems. A nice-looking house with a failing roof or furnace is not a cosmetic rehab.
- No contingency. Experienced buyers read a zero-contingency estimate as inexperience.
- Estimating from the curb. Exterior photos say little about the kitchen, baths, or systems. Get inside or widen your contingency. Lenders make the same mistake with drive-by valuations, which is why a documented repair budget matters on short sales; see our guide to the lender’s BPO.
- Never updating your numbers. Costs change. Refresh your cheat sheet whenever a buyer or contractor gives you a better figure.
The repair cheat sheet
Keep a one-page list of unit costs for your market — per-square-foot paint and flooring, per-window replacement, per-fixture bathroom update, kitchen packages at three price points — and update it every time a buyer corrects you. That sheet is what turns a nervous beginner into someone whose offers get taken seriously.
A good way to build it quickly: ask two or three local contractors or flippers for their typical prices on the items above, and note where they agree. When you are out driving for dollars, practice by guessing the rehab bucket for each property you log, then compare your guess with the photos when a house later lists or sells.
Flipper or landlord: estimate for your likely buyer
Not every cash buyer renovates to the same standard. A flipper selling to a retail buyer will usually budget for a full update of the kitchen, baths, and finishes so the house competes with renovated comps. A buy-and-hold investor renting the property out often chooses durable, lower-cost finishes and may leave some dated items in place if they are functional. Know which type of buyer you expect to sell to, and note on your deal sheet which scope your estimate assumes. That one line prevents a lot of back-and-forth.
Adjust your numbers for the region you work in
The per-square-foot buckets above are a national starting point, and labor is where markets differ most. The 2025 Cost vs. Value report from Zonda (released September 2025) prices the same defined projects across U.S. regions, which makes it a clean way to see how far your market sits from the average. Its numbers describe one standard project scope each, so use them to measure the regional gap, not as a quote for your house.
| Project (2025 job cost) | East South Central | National average | Pacific |
|---|---|---|---|
| Midrange bath remodel | $23,409 (10% below) | $26,138 | $27,710 (6% above) |
| Midrange minor kitchen remodel | $27,034 (5% below) | $28,458 | $29,728 (4% above) |
| Asphalt roof replacement | $25,939 (19% below) | $31,871 | $36,391 (14% above) |
| Vinyl window replacement | $20,328 (8% below) | $22,073 | $23,819 (8% above) |
East South Central is the Census division covering Alabama, Kentucky, Mississippi, and Tennessee; Pacific covers Alaska, California, Hawaii, Oregon, and Washington. The spread is not uniform: the same roof costs about 40% more in the Pacific than in East South Central, while the kitchen gap is closer to 10%. So adjust labor-heavy exterior items more than finishes, and keep checking against local bids, since a regional average still hides big swings between a metro core and its rural counties.
Permits, code, and lead rules belong in the estimate
Beginners tend to treat permits as a rounding error. They are a real line item, and the amount depends entirely on the jurisdiction. Many building departments charge by the valuation of the work: Culver City, California, for example, scales its fee with total valuation and adds plan check at 75% of the permit fee, while Northglenn, Colorado, applies remodel square footage to the ICC building valuation table. Trade permits for electrical, plumbing, or mechanical work can stack on top. Read the local fee schedule before you price a moderate or full-gut job.
For houses built before 1978, budget for lead-safe work. Under the EPA rule, anyone paid to disturb paint in pre-1978 housing must use a lead-safe certified firm, and EPA states that the owner-occupant exemption does not cover people who flip houses for profit. The federal definition in 40 CFR 745.83 exempts only minor repairs that disturb 6 square feet or less of painted surface per room inside, or 20 square feet or less outside, and never window replacement or demolition. A flip with new windows and a gutted kitchen is well past those thresholds, so containment, cleanup, and a certified contractor belong in your number. Fourteen states (including Georgia, North Carolina, Massachusetts, and Wisconsin) run their own EPA-authorized programs, so check which agency oversees the rule where you work. Older homes can also contain asbestos in flooring, ceilings, and pipe wrap; our guide to buying a house with asbestos shows how to budget for testing and abatement.
How your buyer’s lender reads the repair number
Most flippers buying your deal will use a hard money loan, and the lender turns the repair estimate into a scope of work and a draw schedule. Rehab money is usually not handed over at closing. It is held back and released in draws, typically as reimbursement after each phase is finished and verified by an on-site or photo inspection, as both Kiavi and FlipperForce describe the process. Work outside the approved scope may not be reimbursed, and many lenders cap the total loan at a percentage of ARV (70% to 75% is a common example).
For you as the wholesaler, that means a low estimate leaves your buyer with a holdback that runs dry mid-project and a gap they cover in cash, so they re-price it immediately. A clear room-by-room breakdown also helps them plan draws, which makes your deal easier to finance.
Second example: estimating repair costs on a moderate rehab
HYPOTHETICAL deal: a 1,600 sq ft three-bed, two-bath house built in 1962. The kitchen and both baths need full replacement, the panel is an older brand buyers avoid, the roof is near the end of its life, and a sewer camera shows one cracked section. Every figure below is illustrative.
| Line | Basis | Amount |
|---|---|---|
| Interior (moderate bucket) | 1,600 sq ft x $45 | $72,000 |
| Roof | Tear-off and replace | $15,000 |
| Electrical panel | Replace and upgrade | $3,500 |
| Sewer line | Spot repair after camera | $6,000 |
| Permits and plan review | From local fee schedule | $2,500 |
| Lead-safe work (pre-1978) | Certified firm, containment, cleanup | $3,000 |
| Subtotal | $102,000 | |
| Contingency | 10%, house walked | $10,200 |
| Repair estimate | $112,200 |
Now look at it through a lender’s eyes. Say the ARV is $330,000 and your buyer’s lender caps the loan at 75% of ARV, or $247,500. If the lender funds 90% of a $150,000 purchase ($135,000) plus the full $112,200 rehab, the loan is $247,200, just under the cap. Had you shown $85,000 in repairs and the buyer’s contractor came back at $112,000, the buyer would be short about $27,000 in cash they did not plan on, and that is the conversation that kills assignments.
Walkthrough checklist
- Photos of every room, the roof line, the electrical panel, the water heater, and the HVAC data plates
- Notes on ceiling stains, cracks, sticking doors, soft floors, and odors
- Age of the roof, HVAC, and water heater (ask the seller, then verify)
- Count of windows, doors, bathrooms, and fixtures for your line items
- Rehab bucket, big items, contingency, and total written before you leave
Repair estimate FAQ
Do I need a contractor to walk every property?
No. For most cosmetic and moderate rehabs, a careful walkthrough, your cheat sheet, and a buyer’s sanity check are enough. Bring in a contractor or inspector when you see signs of foundation, sewer, or major electrical issues.
What if my buyer’s estimate is much higher than mine?
Ask which line items differ and why. If they are right, update your cheat sheet. If the gap breaks the deal, you may need to renegotiate with the seller during your inspection period, which is one reason to understand the terms in your wholesale contract.
Can I estimate repairs from photos only?
You can make a first pass from photos, but raise your contingency to 15–20% and confirm the major systems before you commit to a number with a buyer.
Should I show my repair estimate to the seller?
Sharing the main items can help a seller understand why a cash, as-is offer is below retail. Keep it factual and focused on the property’s condition.
How much should I budget for permits?
There is no national figure. Cosmetic work like paint and flooring often needs no permit, while roofs, panels, plumbing changes, and kitchen remodels usually do. Pull the fee schedule from the city or county building department’s website and price the permits your scope triggers.
Does the lead paint rule matter if I am only wholesaling?
You are not doing the renovation, so the work rules fall on your buyer and their contractor. It still matters to your estimate: a buyer pricing a pre-1978 house will include lead-safe costs, and an estimate that ignores them looks low.
A wrong repair estimate is the number one reason a contract does not move. Overestimate slightly. A deal with $5,000 of extra margin still assigns; a deal that is $5,000 short does not.
Working a specific market? Our state-by-state wholesaling guides cover the licensing rules, deed records and probate courts for each state and its major cities.
Try it now: drop your repair estimate into the free MAO calculator to see your maximum offer, or into the fix and flip calculator to see your buyer’s profit.
Repairs shape the whole strategy. Light cosmetic work can make a house a good novation candidate, while a heavy rehab points to a flipper. See wholesaling vs fix and flip for how repair scope changes your exit, and our 2026 market report for current flip margins.
Wholesaling guides for top markets
Want someone checking your numbers?
In the Mentorship Program, Victoria reviews every deal before you make the offer. Book a free 20-minute call to see if it fits.
Related guides
Fresh from the blog
Latest wholesaling guides

Massachusetts Foreclosure Process: A Stage-by-Stage Guide for Investors
The Massachusetts foreclosure process is mostly nonjudicial: after a 90-day right-to-cure notice and a short servicemembers case, the lender can…
Read the guide
Tired Landlords: How to Find Them, What to Say, and Deals That Fit
Tired landlords are rental owners who no longer want to deal with tenants, repairs or management and will trade some…
Read the guide
SEO for Real Estate Investors: How to Rank for Motivated Seller Searches
SEO for real estate investors means getting your website in front of homeowners who search for a fast or as-is…
Read the guide
How to Calculate Price Per Square Foot (and When It Misleads)
To calculate price per square foot, divide a home's sale price by its finished, above-grade living area. The math is…
Read the guide
How to Buy an Abandoned House: Find the Owner, Clear Title, Close
To learn how to buy an abandoned house, start with the fact most guides skip: someone still owns it. You…
Read the guide
DealMachine vs PropStream: Which Is Better for Finding Deals?
DealMachine vs PropStream compared: pricing, driving for dollars, list building and which tool suits a new wholesaler.
Read the guide
PropStream vs BatchLeads: Which One Should a Wholesaler Pick?
PropStream vs BatchLeads compared for wholesalers: pricing, data, skip tracing, texting and which one fits your first deals.
Read the guide
Liquidated Damages in Real Estate: How the Clause Protects Wholesalers
Liquidated damages in real estate are a sum, usually the earnest money, that the seller keeps as full compensation if…
Read the guide
Lead-Based Paint Disclosure: What Investors Must Do Before Selling or Renting
A lead-based paint disclosure is required before a buyer or tenant is bound on any home built before 1978. Here…
Read the guide